ARM Earnings Shock: Stock Drops Despite Strong Results
Arm Holdings delivered a stronger-than-expected earnings report for its latest quarter, yet its stock still fell sharply in volatile trading as investors weighed explosive AI-driven demand against supply chain uncertainty and margin pressure. The mixed reaction highlights a growing tension in the semiconductor sector: even record performance is no longer enough if future execution risks remain unclear.
The company continues to benefit from rising demand for AI infrastructure, but its move into designing its own chips has introduced new strategic risks that are now influencing market sentiment.
Strong Earnings Beat Driven by AI Demand
Arm reported revenue of $1.49 billion, marking a 20% year-over-year increase, while adjusted earnings came in at $0.60 per share, beating analyst expectations of $0.58.
A key driver behind this growth was surging demand from AI data centers and cloud computing platforms. Licensing revenue rose sharply, while royalty income continued to expand as more chipmakers adopt Arm-based designs in advanced computing systems.
The company also benefited from growing adoption of its architecture in AI infrastructure, where efficiency and power consumption are becoming critical factors.
Why the Stock Still Fell After Earnings
Despite the strong financial results, Arm’s stock declined in post-earnings trading, at times dropping more than 5%, after initially surging on the results.
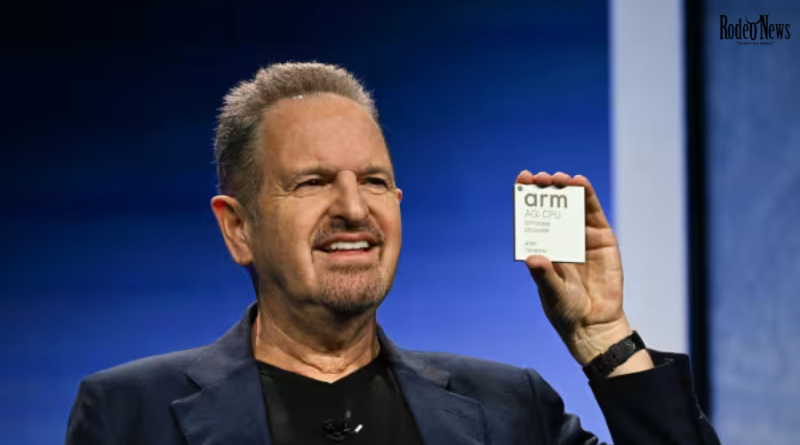
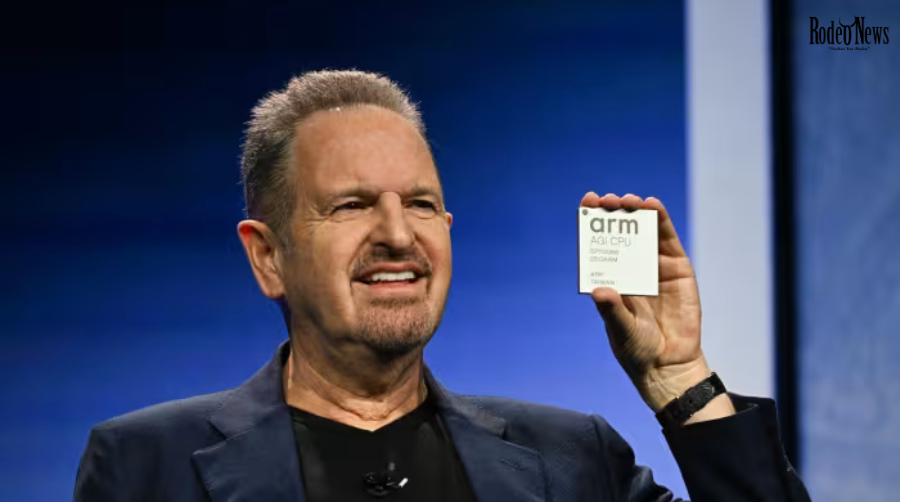
The primary concern from investors centered on supply limitations for Arm’s newly launched AI-focused data center chip, known as the AGI CPU. Management indicated that demand is outpacing production capacity, limiting the company’s ability to fully capitalize on growth opportunities.
This created uncertainty: even though demand is strong, Arm may not be able to convert it into revenue quickly enough.
AI Chip Expansion Creates Long-Term Opportunity—and Risk
One of the biggest strategic shifts in Arm’s history is its decision to move beyond licensing and begin developing its own chips for data centers.
The company has already projected more than $2 billion in demand for its AI server CPU product through FY2027–2028, signaling strong early interest from major tech firms.
However, this transition also introduces new competitive dynamics. Arm is now moving closer to companies that previously only licensed its technology, including major cloud providers and chip designers.
This dual role—as both supplier and competitor—adds complexity to its long-term growth story.
Financial Strength Remains Solid Despite Pressure
Even with market volatility, Arm’s financial performance remains strong:
- Revenue growth above 20% annually
- Strong licensing business expansion
- Rising royalty income from global chip adoption
- High operating margins near 49% in recent reporting periods
However, margins have slightly declined compared to previous highs, reflecting increased investment in research, chip development, and expansion into AI hardware.
Investor Sentiment: Growth vs. Execution Risk
The reaction to Arm’s earnings reflects a broader theme across AI-related stocks in 2026: investors are no longer reacting only to growth, but also to execution capability.
Three major concerns are driving volatility:
- Supply chain constraints limiting chip production
- High expectations priced into the stock valuation
- Transition risk as Arm enters direct chip development
At the same time, bullish analysts point to Arm’s expanding role in AI infrastructure, where its architecture is increasingly used in cloud data centers operated by major hyperscalers.
Outlook: AI Demand Still the Key Driver
Despite short-term volatility, Arm remains positioned at the center of the AI hardware boom. Its technology is already embedded in billions of devices, and its expansion into data center CPUs could significantly increase revenue scale over the next decade.
The company has outlined long-term ambitions of reaching multi-billion-dollar revenue contributions from its AI-focused chip business by the early 2030s.
Still, execution will be critical. Investors are now closely watching whether Arm can convert demand into scalable production without sacrificing margins or alienating long-time licensing partners.
Conclusion
Arm’s latest earnings report reinforces a clear paradox: the company is growing faster than ever, yet its stock is reacting with caution rather than celebration.
Strong AI-driven demand is pushing the business forward, but supply constraints and strategic shifts are introducing new uncertainty.
For investors, Arm is no longer just a stable licensing giant—it is evolving into a high-stakes AI infrastructure player where execution will determine whether today’s opportunity becomes tomorrow’s dominance.