age ALT Text
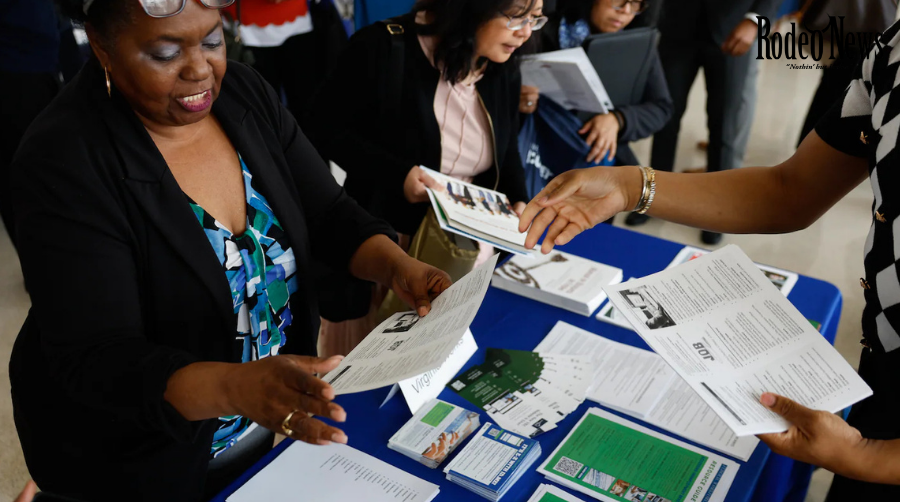
Trump labor market and U.S. jobs data at a manufacturing event
Suggested Featured Image
se a properly licensed editorial image before publishing.
Full Article
Trump Labor Market: 5 Revealing Jobs Shifts
The Trump labor market was weaker during the early part of President Donald Trump’s current term than previously reported, according to newly released federal employment data. The updated figures show that private employers added significantly fewer jobs than earlier estimates suggested between April 2025 and March 2026, offering a clearer picture of a U.S. labor market that was already losing momentum.
The revisions do not show an economic collapse. In fact, the overall adjustment was relatively small compared with the dramatic employment revisions recorded in previous years. However, the details reveal important differences between industries, with manufacturing and retail employment looking weaker while construction, transportation and some government employment performed better than previously estimated.
The latest numbers arrive at a politically sensitive moment for the Trump administration. Americans continue to face concerns about prices, while policymakers and economists are watching closely for signs that businesses are becoming more cautious about hiring.
Here are five important developments revealed by the latest data.
1. Trump Labor Market Data Shows Fewer Private-Sector Jobs
The most significant finding is the downward revision to private-sector employment.
The Bureau of Labor Statistics, or BLS, said its preliminary benchmark revision reduced the March 2026 estimate for total private employment by 178,000 jobs, or about 0.1 percent. Total nonfarm employment was revised down by 79,000 jobs, also about 0.1 percent.
The numbers cover the period from March 2025 to March 2026 and are based on a comparison between the BLS employment survey and more comprehensive employment records collected through state unemployment insurance systems.
That distinction matters.
Monthly employment reports are based largely on surveys of businesses. Those surveys provide timely information, but they are estimates and can later be adjusted when more complete administrative records become available.
The annual benchmark process is designed to bring the survey estimates closer to those more comprehensive counts.
For the Trump labor market, the latest revision therefore provides a more complete look at employment during the first year of the administration.
The Washington Post reported that private employers added 178,000 fewer jobs than previously reported during the period. The overall revision, however, was partly offset by stronger government employment.
Read the Washington Post report
2. Manufacturing Jobs Were Weaker Than Previously Thought
Manufacturing is one of the most important parts of the latest revision because rebuilding American factory employment has been a major economic goal for Trump.
The revised data showed that manufacturing employment was 67,000 jobs lower than previously estimated for March 2026. That represents a 0.5 percent downward revision for the sector.
The result is notable because tariffs have been central to the administration’s economic strategy.
Trump has repeatedly argued that tariffs can encourage companies to produce more goods inside the United States. Supporters say stronger domestic production could eventually support industrial employment and investment.
However, the latest employment revision shows that manufacturing had not yet produced the broad job gains that such policies might be expected to generate.
That does not prove that tariffs caused the manufacturing losses. Employment is influenced by many factors, including consumer demand, business investment, automation, global trade conditions and interest rates.
Still, the figures highlight a challenge for the administration.
If manufacturing employment remains weak, it could become harder to demonstrate that trade policies are producing rapid improvements for American workers.
Reuters has also reported that U.S. factory employment had been under pressure, with manufacturing jobs falling during the early months of Trump’s current term.
3. Retail Employment Took a Major Hit
Retail was another major weak spot in the revised Trump labor market data.
According to the BLS, retail employment was revised downward by approximately 154,600 jobs, representing a 1 percent revision. Wholesale trade was also revised lower by about 86,200 jobs.
The retail figures are particularly important because retail businesses employ millions of Americans and are closely connected to consumer spending.
A weaker retail employment picture can indicate that companies are becoming more cautious about staffing stores and distribution operations. It can also reflect changing consumer behavior, automation and shifts toward online commerce.
The latest numbers should therefore be viewed as part of a broader economic picture rather than as evidence of one single cause.
Consumers have faced higher prices, while businesses have dealt with uncertainty surrounding trade policy and the broader economic outlook.
Those pressures can influence hiring decisions.
When companies are uncertain about future sales, they may postpone expansion plans or reduce the pace of new hiring even if they are not conducting large-scale layoffs.
That creates a labor market that can appear stable on the surface while becoming increasingly difficult for job seekers.
4. Construction and Data Centers Were Bright Spots
Not every part of the revised Trump labor market picture was negative.
Construction employment was revised 62,000 jobs higher than previously estimated. Utilities also received an upward revision, while transportation and warehousing employment was revised upward by about 135,100 jobs.
The construction figure is especially significant.
The Washington Post reported that construction and utilities together recorded about 70,000 more jobs than previously estimated during the period, with the data-center boom contributing to expansion in those areas.
The rapid growth of artificial intelligence infrastructure has created demand for data centers, electricity generation, construction workers and related services.
That trend could become increasingly important for the U.S. economy.
Technology companies are investing heavily in computing infrastructure, and that investment requires large physical facilities as well as power and transportation networks.
As a result, the labor market may be experiencing a shift in where employment growth is occurring.
Traditional sectors such as retail and manufacturing can remain under pressure while construction, infrastructure and technology-related industries expand.
This is one reason headline employment figures do not always tell the complete story.
5. The Jobs Market Is Cooling, But It Is Not Collapsing
Perhaps the most important takeaway is that the latest numbers point toward a cooling labor market rather than an outright collapse.
Guy Berger, director of economic research at the Burning Glass Institute, described the revised figures as consistent with a labor market that is cooling, although the decline is happening more slowly than in the previous two years, according to The Washington Post.
That distinction is important.
The U.S. economy still has millions of employed workers, and unemployment remains relatively low. At the same time, job creation has become less broad and less consistent across industries.
Recent monthly employment data reinforces that concern.
In July, U.S. employers unexpectedly shed 23,000 jobs, while revisions reduced May and June payroll gains by a combined 103,000 jobs. The unemployment rate nevertheless edged down to 4.1 percent, partly because fewer people were participating in the labor force.
This creates a complicated picture.
A low unemployment rate can make the labor market appear healthy. But if fewer people are working or looking for jobs, and employers are creating fewer positions, the headline unemployment figure may not fully capture the challenges facing workers.
What the BLS Revision Means for the Economy
The latest revision is part of the BLS’s normal annual benchmarking process.
The agency compares its employment estimates with more comprehensive employment counts derived largely from state unemployment insurance tax records. These records cover nearly all employers and provide a broader measure of employment than the monthly survey alone.
The August 28 revision is preliminary.
The BLS said the final benchmark revision will be released in February 2027, when the January 2027 Employment Situation report is published. Until then, the current numbers should not be treated as the final historical record.
U.S. Bureau of Labor Statistics employment data
That qualification is particularly important because employment revisions have become politically sensitive.
Last year, Trump fired BLS Commissioner Erika McEntarfer after criticizing a weak jobs report and claiming, without evidence, that employment figures had been manipulated. Subsequent large revisions intensified political arguments over the reliability of government employment data.
Economists have generally rejected claims that the employment data were deliberately manipulated. The BLS says its benchmarking process exists precisely because early survey-based estimates can differ from more comprehensive administrative records.
Why the Revision Matters for Trump
The economic significance of the new figures extends beyond statistical accuracy.
Trump campaigned heavily on promises of stronger economic growth, more domestic production and improved opportunities for American workers. A labor market that is weaker than previously reported makes those promises harder to evaluate positively.
At the same time, the administration can point to areas where the numbers are encouraging.
Construction employment was stronger than initially estimated. Transportation and warehousing also received a substantial upward revision. Government employment was revised higher by 99,000 jobs.
The result is a mixed economic picture.
Some sectors are expanding quickly because of infrastructure and technology investment. Others are losing jobs or failing to produce the employment growth expected by policymakers.
That uneven performance may become increasingly important as the United States approaches the 2026 midterm elections.
Economic conditions, particularly prices and employment, are likely to remain major issues for voters.
What Comes Next for the Trump Labor Market?
The next major test will come from upcoming employment reports.
The BLS has scheduled its August 2026 Employment Situation report for September 4, providing another opportunity to determine whether the recent slowdown is temporary or part of a longer trend.
Investors and economists will likely watch several indicators closely.
First is payroll growth. Continued weak or negative monthly job creation would reinforce concerns that businesses are pulling back.
Second is unemployment. A rising unemployment rate would signal that the cooling labor market is becoming more painful for workers.
Third is labor-force participation. If more Americans leave the workforce, the unemployment rate could remain deceptively low even as job opportunities weaken.
Finally, economists will watch wages and inflation.
The Federal Reserve faces a difficult balancing act when employment growth slows while inflation remains elevated. Cutting interest rates can support hiring and investment, but easing policy too quickly could risk reigniting price pressures.
The Bigger Picture
The latest Trump labor market data does not tell a simple story of economic success or failure.
Instead, it shows an economy undergoing a significant transition.
Private-sector employment was weaker than previously estimated. Manufacturing and retail were among the biggest areas of downward revision. At the same time, construction, transportation, utilities and some other sectors performed better than earlier data suggested.
The revision also provides an important reminder about economic statistics: initial numbers are not always final.
Employment data is routinely updated as more information becomes available. The latest figures should therefore be seen as a clearer estimate of the past rather than a sudden change in the economy itself.
For the Trump administration, however, the timing is significant.
The revised figures suggest that the labor market entered the administration’s first year on a weaker foundation than earlier reports indicated. Whether Trump’s policies can reverse that trend — particularly in manufacturing and other industries targeted by his economic agenda — will depend on what happens next.
For American workers, the most important question is simpler: Will businesses start hiring more broadly again?
The answer will become clearer as new employment reports arrive and the BLS completes its final benchmark revision in early 2027.
Internal Link Suggestions
Since no target domain was provided, add these after publication using your site’s existing URLs:
- U.S. jobs report and employment news
- Trump economy and economic policy
- U.S. inflation and Federal Reserve coverage
- Manufacturing jobs and U.S. industry
- Latest U.S. economic news