Stock Market Today: 5 Key Moves Revealed
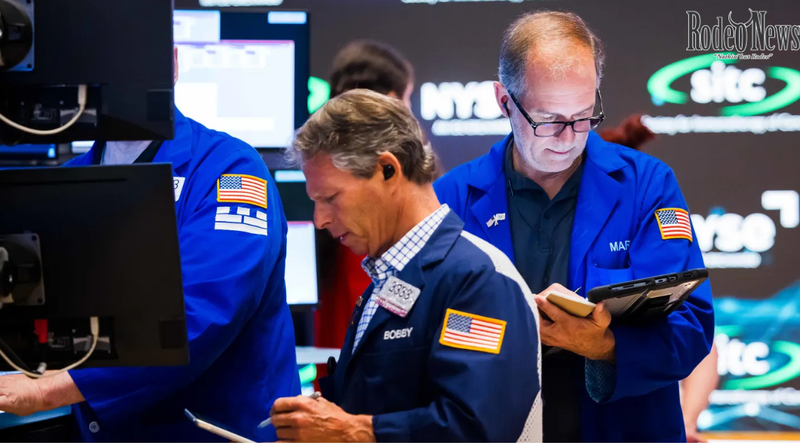
The stock market today delivered a mixed performance on Monday, October 12, 2026, as investors weighed rising oil prices, weakness in technology shares, and the start of a closely watched corporate earnings season. The Dow Jones Industrial Average advanced, while the S&P 500 and Nasdaq Composite ended the session lower.
The trading session reflected a market balancing optimism about corporate profits against uncertainty surrounding inflation, geopolitical developments, and the outlook for interest rates. Investors were also preparing for a busy week of economic releases and financial results from major U.S. banks.
According to the Associated Press, the Dow gained approximately 0.4% to close at 51,850.55. The S&P 500 slipped 0.1% to 7,807.24, while the Nasdaq Composite declined 0.4% to 27,245.90.
Although the declines were relatively modest, the uneven performance highlighted an important question for investors: Can the broader market continue advancing if technology shares lose momentum and energy costs remain elevated?
Here are five major developments that shaped the U.S. stock market on October 12 and the factors investors were watching as the new trading week began.
1. Stock Market Today: Dow Gains as Nasdaq Falls
The most notable development was the divergence between the Dow Jones Industrial Average and the technology-heavy Nasdaq Composite.
The Dow rose 0.4%, extending its recent advance as investors found opportunities outside some of the market’s most expensive technology stocks. Meanwhile, the S&P 500 edged lower, and the Nasdaq dropped 0.4%.
The difference between the indexes illustrates how individual sectors can influence the broader market in different ways.
The Dow includes a selection of established companies across industries such as finance, healthcare, consumer goods, and technology. The Nasdaq Composite has substantial exposure to technology and growth-oriented businesses, making it particularly sensitive to changes in investor expectations for future earnings.
When investors become concerned about valuations, borrowing costs, or the sustainability of artificial intelligence-related spending, technology stocks can experience greater pressure than more established businesses.
Monday’s performance suggested that investors were becoming more selective rather than abandoning stocks altogether.
However, one session does not establish a lasting market trend. Investors will need to watch subsequent trading sessions, earnings reports, and economic data to determine whether the divergence between the indexes continues.
For market participants, the key question is whether strength in financial, energy, and other established businesses can offset weakness in technology shares.
2. Technology Stocks Face Pressure Amid Valuation Concerns
Technology shares were among the important sources of weakness during Monday’s session.
Investors have continued to examine whether the substantial spending associated with artificial intelligence can translate into sustainable revenue growth and stronger profits. Although AI-related demand has created opportunities for semiconductor manufacturers, cloud computing providers, and software companies, it has also raised expectations for future performance.
Those expectations can create volatility.
When stock prices already reflect ambitious growth assumptions, even a relatively small change in earnings forecasts or competitive conditions can trigger a significant market reaction.
Competition in the memory-chip industry was one factor attracting attention. Investors were evaluating the implications of increasing competition from Chinese manufacturers, including ChangXin Memory Technologies, for established semiconductor businesses.
Companies connected to AI infrastructure also experienced pressure. Market coverage from Investors.com highlighted declines in chipmakers and AI-related equipment companies during Monday’s trading.
Nevertheless, weakness in some technology shares does not necessarily mean that the long-term AI investment cycle has ended. Demand for computing capacity, data centers, networking equipment, and advanced chips may continue to support parts of the industry.
The challenge for investors is distinguishing between companies with durable earnings prospects and those whose valuations leave little room for disappointment.
As third-quarter earnings arrive, revenue growth, profit margins, capital expenditure, and management guidance are likely to become increasingly important.
3. Rising Oil Prices Add Another Concern for Investors
Energy prices provided another important backdrop for the stock market.
Brent crude, an international oil benchmark, rose approximately 1.8% to $106.65 per barrel on Monday, according to the Associated Press.
Higher oil prices can affect companies and consumers in several ways. Airlines, transportation businesses, manufacturers, and logistics providers may face higher operating expenses. Companies that cannot easily pass those costs to customers could experience pressure on profit margins.
Consumers may also have less money available for discretionary purchases when gasoline, heating, and transportation costs rise.
These effects can complicate the economic outlook, particularly when inflation is already a central concern for financial markets.
Higher energy costs can also influence expectations for monetary policy. If rising fuel prices contribute to persistent inflation, investors may become less confident that the Federal Reserve can lower interest rates as quickly as previously anticipated.
However, the impact is not uniform across the market.
Oil producers and some energy companies may benefit from stronger commodity prices, especially when higher prices are accompanied by solid demand and disciplined production.
That creates a divide between energy producers and businesses that consume substantial amounts of fuel.
Investors therefore need to consider both the direction of oil prices and the reasons behind the movement. Supply disruptions, geopolitical tensions, stronger demand, and changes in production can have different implications for corporate earnings and the broader economy.
For the coming sessions, developments in global energy markets will remain an important factor to monitor alongside company results and inflation figures.
4. Major Bank Earnings Put Financial Stocks in Focus
The start of the third-quarter earnings season was another major consideration for investors.
JPMorgan Chase, Citigroup, and Wells Fargo were scheduled to report results on Tuesday, October 13. Their earnings could provide fresh information about consumer spending, loan demand, credit quality, business activity, and the health of the U.S. financial system.
Bank earnings often offer a useful snapshot of economic conditions because financial institutions serve households, businesses, and institutional clients across multiple industries.
Investors will be looking beyond headline profit figures.
Revenue from lending and trading, net interest income, loan-loss provisions, deposit costs, and management commentary could all influence how the market interprets the results.
Credit quality is especially important. If consumers and businesses are having difficulty meeting financial obligations, banks may need to set aside more money to cover potential losses. Higher provisions can reduce profitability and raise concerns about economic resilience.
On the other hand, steady loan performance and healthy business activity could reinforce confidence in corporate earnings.
Investment banking activity and financial-market volatility may also affect results, although the influence will differ across institutions.
The reports could have implications beyond the financial sector. Strong results and constructive guidance may support confidence in the wider corporate earnings outlook, while disappointing results could raise questions about economic momentum.
Investors should also distinguish between one-time gains and sustainable operating performance.
A bank that exceeds earnings expectations because of an unusual item may receive a different market response from one that demonstrates stronger underlying revenue, controlled expenses, and stable credit quality.
5. Inflation and Retail Sales Data Could Shape Market Direction
Economic data was another major focus as investors prepared for the remainder of the week.
The September Consumer Price Index report was scheduled for Wednesday, October 14, while the Producer Price Index and retail sales data were expected on Thursday, October 15.
These releases could influence expectations for inflation, consumer demand, and the Federal Reserve’s future policy decisions.
The Consumer Price Index measures changes in prices paid by consumers for a broad range of goods and services. The Producer Price Index tracks price changes received by domestic producers and can provide additional information about cost pressures within the economy.
Retail sales figures, meanwhile, offer insight into consumer spending, an important driver of U.S. economic activity.
Stronger-than-expected inflation could put pressure on stocks if investors conclude that interest rates may remain elevated for longer. Higher rates can increase financing costs and reduce the present value investors assign to future corporate earnings.
Growth-oriented companies are often particularly sensitive to shifts in rate expectations because a larger portion of their valuations may depend on profits anticipated years into the future.
Conversely, softer inflation could support expectations for a more accommodative monetary policy, provided the figures do not also signal a sharp deterioration in economic activity.
Retail sales data may help clarify that balance.
Resilient consumer spending could support corporate revenue forecasts, while a slowdown might raise concerns about demand and earnings growth. Yet weaker spending could also ease some inflationary pressures, creating a more complicated picture for policymakers.
Investors will therefore be assessing the combination of figures rather than relying on a single headline number.
The Federal Reserve’s next interest-rate decision, scheduled for October 28, adds further importance to the incoming data.
Market participants should remember that economic releases can produce sharp short-term price movements, particularly when the results differ materially from expectations.
What Monday’s Market Performance Means for Investors
The mixed performance on October 12 demonstrates why investors should avoid judging market conditions solely by whether one major index finishes higher or lower.
The Dow’s gain showed that parts of the market remained resilient. Meanwhile, declines in the S&P 500 and Nasdaq highlighted lingering uncertainty surrounding technology valuations, energy costs, and the economic outlook.
The broader picture was not uniformly negative.
The Associated Press reported that the major indexes remained substantially higher for the year through Monday’s close. The S&P 500 had gained approximately 14% year to date, while the Dow was up 7.9% and the Nasdaq had advanced 17.2%.
Those gains provide context for the latest session, but they do not guarantee further advances.
Markets can experience pullbacks even during longer-term uptrends. Investors also need to account for valuation risks, unexpected economic developments, and changes in corporate earnings expectations.
A practical approach is to monitor several indicators together.
First, compare performance across sectors rather than focusing exclusively on index headlines. Second, examine whether companies are delivering earnings growth that supports their valuations. Third, watch inflation and interest-rate expectations because they affect borrowing costs and stock valuations.
Finally, consider the difference between temporary volatility and a sustained deterioration in business fundamentals.
For long-term investors, maintaining a diversified portfolio and aligning investments with personal risk tolerance can be more useful than attempting to predict every daily market move. Short-term traders, meanwhile, should recognize that data releases and earnings announcements can increase volatility and execution risk.
Neither approach eliminates the possibility of losses.
Outlook: What to Watch Next in the Stock Market
The next several trading sessions could help determine whether Monday’s mixed performance represents temporary consolidation or a more meaningful shift in investor preferences.
The immediate catalysts include major bank earnings, September inflation data, retail sales, producer prices, and further developments in global energy markets.
Technology shares will also remain in focus as investors assess competition, AI-related spending, and the outlook for future earnings.
Three broad scenarios deserve attention.
In the first, strong corporate results and relatively favorable inflation data could reinforce confidence in the market’s earnings outlook. Such a combination might help support equities across several sectors.
In the second, persistent inflation and rising energy costs could complicate the outlook for interest rates. That scenario could place additional pressure on highly valued stocks and businesses with limited pricing power.
In the third, results could be mixed, leaving investors to distinguish between companies with strong fundamentals and those facing weaker demand or rising costs.
None of these outcomes is certain, and market prices can move differently from expectations.
Investors should therefore focus on verified data, company-specific fundamentals, and changes in the economic outlook rather than assuming that a single trading session predicts what comes next.
Final Takeaway
The stock market today reflected a cautious balance between optimism about corporate earnings and concerns about technology valuations, oil prices, and inflation.
The Dow Jones Industrial Average advanced on October 12, 2026, while the S&P 500 and Nasdaq Composite slipped. Attention now turns to major bank earnings and economic reports that could influence expectations for growth and interest rates.
The coming week may provide a clearer picture of whether corporate profits can sustain the market’s gains amid a more complicated economic backdrop.
For investors, the central lesson is straightforward: Monitor earnings quality, inflation trends, and developments across multiple sectors instead of drawing conclusions from one day’s market movement.
Market figures in this article refer to the October 12, 2026, U.S. trading session. This article is for informational purposes only and does not constitute investment advice.