Marvell Stock: 5 Key AI Earnings Takeaways
Marvell stock fell sharply after the semiconductor company reported another record quarter, even though its earnings and revenue slightly exceeded Wall Street expectations.
The reaction may seem surprising at first. Marvell Technology reported fiscal second-quarter revenue of $2.739 billion, a company record that was 37% higher than a year earlier. Non-GAAP earnings reached 94 cents per diluted share, also ahead of expectations.
Yet shares dropped as much as 7.6% in premarket trading Friday, according to Barron’s. The decline came after Marvell had already gained about 184% in 2026, creating extremely high expectations for the company’s artificial intelligence opportunity.
The latest report therefore offers an important lesson for investors watching AI semiconductor stocks: strong numbers do not always produce a rising share price.
Here are five key takeaways from Marvell’s latest earnings report.
1. Marvell Stock Still Has Powerful AI Growth
The biggest positive from the report is clear: Marvell’s underlying business continues to expand rapidly.
The company generated $2.739 billion in revenue during its fiscal second quarter. Revenue increased 37% year over year and came in $39 million above the midpoint of Marvell’s previous guidance.
The data-center business was the biggest driver.
Marvell reported data-center revenue of approximately $2.17 billion, representing a 46% increase from the same quarter a year earlier. Data-center sales accounted for roughly 79% of the company’s total revenue during the quarter.
That performance demonstrates how deeply Marvell is tied to the expansion of artificial intelligence infrastructure.
AI companies need much more than powerful processors. Large-scale AI systems also require networking, connectivity, custom silicon, memory-related technologies and other infrastructure that allows enormous quantities of data to move efficiently through data centers.
Marvell participates in several of those areas.
CEO Matt Murphy said AI-related bookings remained exceptionally strong and that revenue growth is expected to accelerate during the remainder of fiscal 2027. The company also pointed to broad strength across its data-center portfolio.
For the long-term bull case, that is important.
The latest results do not indicate that AI demand is slowing. Instead, they suggest that Marvell continues to benefit from the enormous capital spending required to build next-generation AI infrastructure.
2. Marvell Earnings Beat Estimates, But Not by Enough
Marvell’s earnings were better than expected.
The company reported adjusted earnings of 94 cents per share compared with Wall Street expectations of approximately 93 cents. Revenue of $2.739 billion also narrowly exceeded estimates of about $2.72 billion.
On a GAAP basis, Marvell reported net income of $308 million, or 33 cents per diluted share.
Non-GAAP net income was $865.9 million, or 94 cents per diluted share. Operating cash flow reached $605.5 million during the quarter.
Those are strong results.
However, Marvell stock was not trading like an ordinary semiconductor company heading into the report.
Shares had already risen dramatically during 2026 as investors became increasingly optimistic about Marvell’s position in AI infrastructure. That rally effectively raised the bar for the earnings report.
A small earnings beat was therefore not enough.
Investors wanted evidence that Marvell’s growth could accelerate substantially beyond what was already reflected in the stock price.
This is one of the most important points for understanding the post-earnings decline.
The company did not necessarily report disappointing results. Rather, investors appeared disappointed relative to exceptionally high expectations.
That distinction could continue to influence Marvell stock in the months ahead.
3. Marvell Raised Its Forecasts for 2027 and 2028
Despite the negative market reaction, Marvell’s long-term outlook became more optimistic.
The company raised its fiscal 2027 revenue outlook to approximately $12 billion, compared with its previous forecast of about $11.5 billion.
More importantly, Marvell increased its fiscal 2028 revenue forecast to approximately $18 billion, up from $16.5 billion previously.
That is a substantial increase in expected future revenue.
The upgraded outlook reinforces management’s belief that AI infrastructure demand will remain a powerful growth engine.
Marvell also expects its custom business to accelerate during the second half of fiscal 2027. Custom silicon has become increasingly important as major cloud companies develop their own AI processors instead of relying exclusively on general-purpose chips.
That trend could become a major opportunity for Marvell.
Hyperscalers are investing heavily in custom chips because purpose-built processors can be designed for specific workloads and potentially improve efficiency, performance and cost.
Marvell’s ability to help major technology companies develop those solutions gives the company exposure to a rapidly expanding market.
However, investors are now asking a tougher question: how quickly will those opportunities translate into revenue?
That question is especially important because of Marvell’s expanded relationship with Google.
4. The Google AI Chip Deal Is Huge — But Timing Matters
The Google relationship has become one of the biggest elements of the Marvell investment story.
Marvell recently expanded its collaboration with Google on custom artificial intelligence chips and related infrastructure. The agreement also includes a warrant arrangement that could give Google the ability to acquire a significant stake in Marvell if certain conditions are met. Barron’s reported that the warrant could represent a potential $12.2 billion stake.
The partnership covers more than processors.
It is connected to areas including AI processing, storage, networking and memory infrastructure, making it potentially significant for Marvell’s long-term growth strategy.
However, there is a timing issue.
Marvell indicated that some of the more significant revenue contribution associated with the Google opportunity is not expected until fiscal 2029 and beyond.
That appears to have frustrated some investors.
The market had already incorporated substantial expectations around Marvell’s AI partnerships. Investors may have been hoping to see more immediate financial benefits from the Google relationship.
Instead, the biggest contribution could take several years to materialize.
This does not necessarily weaken the long-term opportunity.
It simply changes the timing.
For investors, a large revenue opportunity arriving in 2029 is fundamentally different from the same opportunity arriving in 2027.
That difference matters greatly when a stock has already experienced a huge rally.
5. Marvell Stock Has Another Major Catalyst in October
The next major event for investors could be Marvell’s investor day.
The company plans to hold its investor day on October 6, 2026, when management is expected to provide additional details about its long-term strategy for AI infrastructure.
That event could become particularly important following the latest earnings reaction.
Investors will likely want more information about the company’s custom-chip pipeline, data-center growth expectations and the financial impact of major hyperscaler relationships.
Management could also provide additional detail about how Marvell expects its AI business to develop over the next several years.
The investor day may therefore help answer a critical question:
Is Marvell’s current valuation justified by the company’s long-term growth opportunity?
If management presents stronger-than-expected targets, details about new customer programs or evidence that custom AI chip demand is accelerating faster than expected, sentiment could improve.
On the other hand, if the company largely repeats expectations that investors already know, the market may continue focusing on valuation and the timing of future revenue.
Marvell’s Third-Quarter Guidance Is Also Strong
The near-term outlook remains encouraging.
Marvell expects fiscal third-quarter revenue of approximately $3.15 billion, plus or minus 5%.
The company expects non-GAAP diluted earnings of approximately $1.10 per share, plus or minus five cents.
That revenue forecast is above the roughly $3.03 billion analysts were expecting before the earnings report, according to current market coverage.
The earnings outlook was also slightly ahead of expectations.
That means the immediate operating picture remains healthy.
Marvell is not forecasting a slowdown. Instead, management expects growth to accelerate.
The challenge is that the stock market is looking farther into the future.
When a company has already risen more than 180% in a year, investors begin focusing on longer-term earnings power rather than simply the next quarter.
That is why Marvell’s guidance can be simultaneously bullish for the business and insufficient to support the stock price.
Why Marvell Stock Fell After Good News
The market reaction ultimately comes down to expectations and valuation.
Marvell has become one of the major beneficiaries of the AI infrastructure boom. Its shares had already climbed dramatically, making the company a popular way for investors to gain exposure to custom AI chips and data-center growth.
That creates a difficult situation.
When expectations become extremely high, even excellent results can trigger selling.
Investors may have been looking for a much larger earnings beat, faster Google-related revenue or more aggressive long-term guidance.
Instead, they received solid results, modest earnings beats and higher forecasts that still suggested some of the biggest Google-related opportunities would arrive later.
As a result, investors appear to have taken profits.
This does not automatically mean the AI growth story has broken.
In fact, the operating numbers suggest the opposite.
Data-center revenue increased 46%. Total revenue climbed 37%. The company raised its 2027 and 2028 revenue targets. And management said AI-related bookings remain exceptionally strong.
The problem is the gap between business momentum and stock-market expectations.
What Could Drive Marvell Stock Next?
Several factors could determine where Marvell stock goes next.
AI Data-Center Demand
The company’s data-center business is now responsible for the overwhelming majority of revenue.
Continued growth in this segment will therefore be essential.
If AI infrastructure spending remains strong, Marvell could continue reporting rapid revenue growth.
Custom AI Chips
Custom silicon is becoming an increasingly important part of the AI hardware ecosystem.
Companies such as Google and other hyperscalers have strong incentives to develop chips optimized for their own workloads.
Marvell’s ability to support these programs could become a major source of future revenue.
Google Revenue Timing
Investors will continue watching the Google relationship closely.
The partnership is strategically important, but the timing of its financial contribution matters.
If revenue begins arriving earlier or ramps faster than expected, it could provide a significant boost to investor sentiment.
Valuation
Perhaps the biggest short-term risk is valuation.
A company can have excellent fundamentals and still experience a significant stock decline if investors believe the shares have become too expensive.
Marvell’s enormous 2026 rally means valuation will remain a major consideration.
The Bigger Picture for Marvell Stock
The latest earnings report creates a mixed picture for investors, but the underlying business remains compelling.
Marvell delivered record revenue of $2.739 billion and grew sales 37% year over year. Data-center revenue rose 46%, while management raised its revenue outlook for both fiscal 2027 and fiscal 2028.
Those numbers demonstrate strong operating momentum.
At the same time, the market reaction shows that investors are demanding more.
Marvell stock had already climbed roughly 184% in 2026 before the earnings report. That enormous gain meant the company entered earnings season with a very high bar.
The Google partnership adds another layer to the story.
The long-term opportunity is substantial, but some of the most important revenue benefits may not arrive until fiscal 2029 and beyond.
That could keep investors focused on execution, valuation and the pace of AI infrastructure spending.
The October investor day could provide the next major test.
If Marvell can demonstrate that its custom-chip pipeline is expanding rapidly and that hyperscaler demand will translate into accelerating revenue, the recent pullback could eventually look like a normal correction after a huge rally.
If investors remain concerned that too much future growth is already priced into the shares, volatility could continue.
For now, the most important conclusion is that the Marvell stock decline does not appear to reflect a collapse in the company’s AI business.
Instead, it reflects a market that has become extremely demanding.
Marvell is growing quickly. AI demand remains strong. The company’s long-term revenue forecasts are rising.
But after such a powerful stock-market rally, investors want more than good news.
They want exceptional news.
That is the challenge Marvell now faces as it tries to turn its growing AI opportunity into sustained earnings growth and justify the expectations surrounding its stock.
Suggested Internal Links
Add relevant links from your website using anchor text such as:
- AI semiconductor stocks to watch
- Best AI stocks for investors
- Latest semiconductor earnings
- Nvidia earnings and AI chip demand
- Technology stocks to watch in 2026
Credible External Sources
Image Recommendation
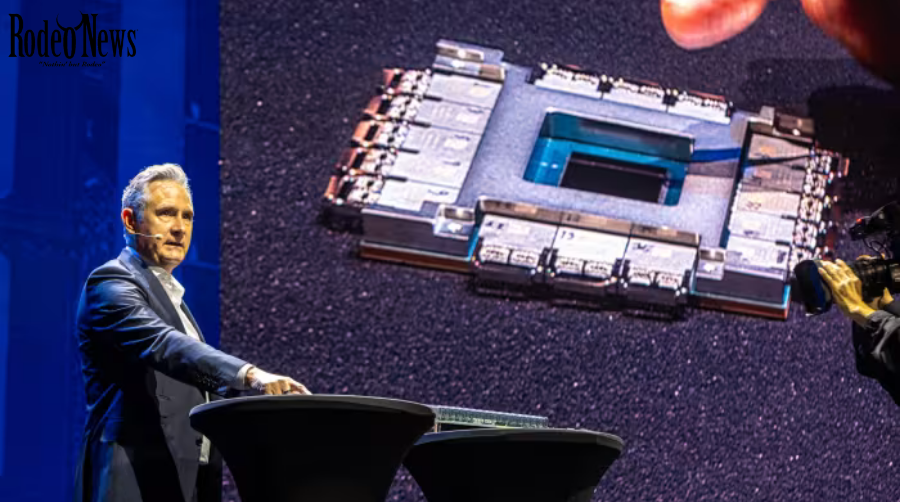
Primary image: Marvell Technology semiconductor/data-center hardware or a professional stock-market image featuring Marvell Technology.
WordPress ALT Text:
Marvell stock falls after strong AI earnings and Google chip deal
Suggested image caption:
Marvell’s strong AI-driven earnings failed to satisfy investors after a huge 2026 stock rally.