When assessing SkyWest Inc. (NASDAQ: SKYW), several valuation metrics suggest the company may be trading at a discount — even as it undertakes strategic investments in its fleet and rewards shareholders.
Strong Free Cash Flow Outlook
SkyWest’s latest twelve-month free cash flow is reported at approximately US$312.5 million, with forecasts pointing to around US$546 million by 2027 and further growth to US$730.8 million by 2035.
Using a discounted cash flow (DCF) model, one analysis arrives at an intrinsic value of ~US$204.39 per share, compared to a recent share price near US$99.07 — implying a potential 51.5% discount to intrinsic value.
Traditional Metrics: PE and EV/EBITDA
On a price-to-earnings (P/E) basis, SkyWest trades around 9.8× earnings, with a calculated “fair ratio” of 10.8× — suggesting the market may be undervaluing the company relative to its fundamentals.
Meanwhile the enterprise value to EBITDA (EV/EBITDA) ratio is around 9.23×, slightly higher than the industry median (~8.5×) for transportation firms, indicating perhaps a modest premium in that metric.
Why the Undervaluation Narrative?
Several operational and strategic factors bolster the bullish case:
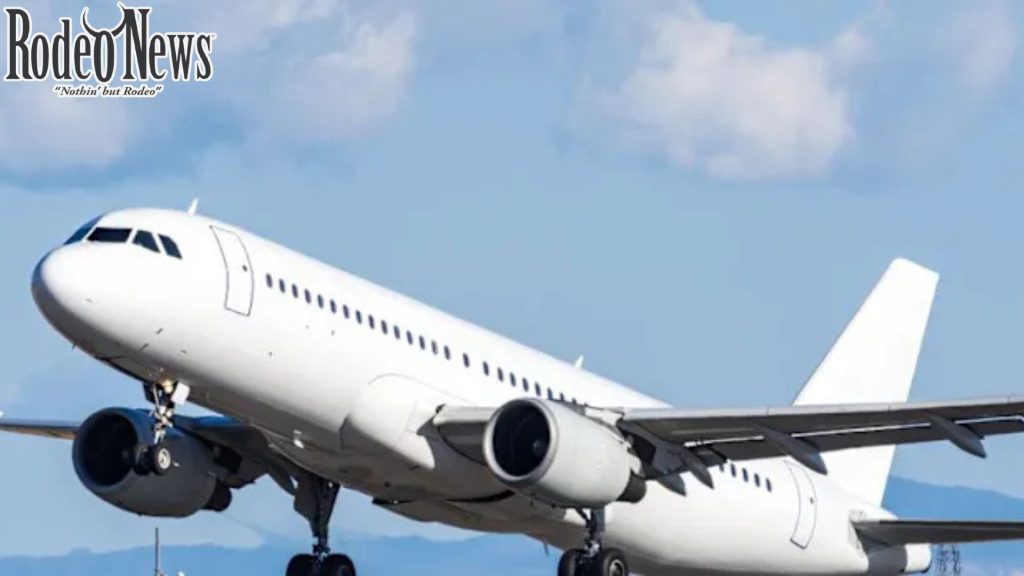
Fleet refresh and modernization: SkyWest has multi-year agreements in place, for example acquiring 16 new E175 aircraft from Embraer S.A. to be delivered in 2027-28, replacing older CRJ700 and CRJ900 models under contract with major carriers.
Nasdaq
Solid balance sheet and shareholder-friendly moves: At the end of Q2 2025, the company held approximately US$727 million in cash and marketable securities, while total debt was declining. SkyWest expanded its share repurchase program by US$250 million and repurchased ≈ 195,000 shares in Q2.
Together, these moves support a narrative that the company is not only investing for future growth but also actively returning capital to shareholders.
Risks to Consider
The optimistic valuation hinges on assumptions that growth in free cash flow will materialize and that cost dynamics (pilot labour, fuel, maintenance) remain favourable. Some analysts estimate only a ~9.5% discount relative to fair value while others project ~24-50% undervaluation depending on scenario.
Sahm
Moreover, transportation and airline-region exposure brings cyclicality and sensitivity to economic swings, labour shortages and regulatory risks.
The Bottom Line
Based on a combination of DCF modelling, multiple valuation ratios and strategic operations, SkyWest appears to offer a compelling value proposition. Its modernization efforts and shareholder-return actions add further appeal.
However, investors should weigh the upside potential against execution risk, macro sensitivities and how much of the “undervalued” gap the market has already priced in