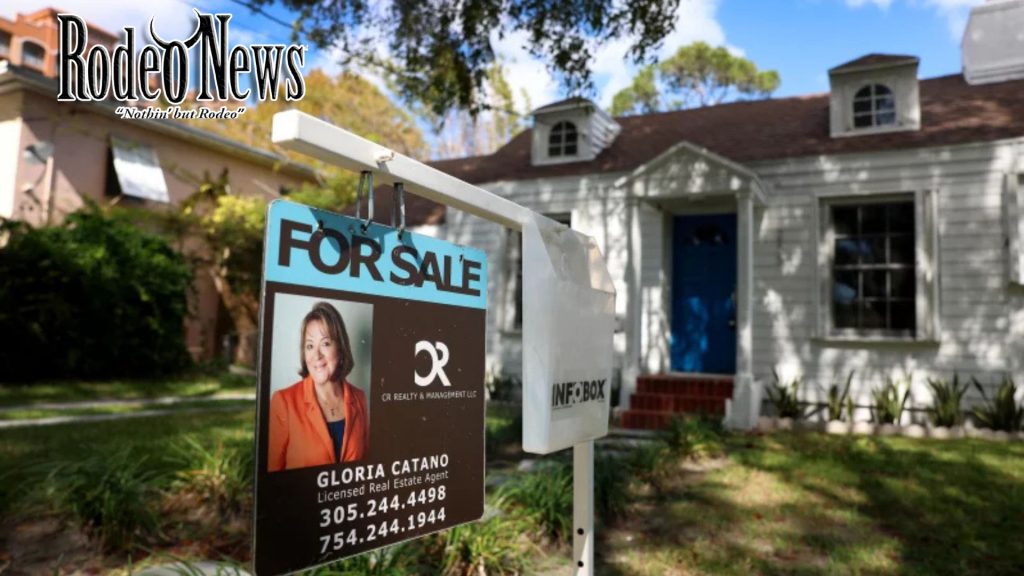
The notion of a 50-year mortgage — stretching home loan terms to half a century — has entered the spotlight under the Donald Trump administration as a proposed tool to ease housing affordability. On the surface, the idea seems straightforward: lower monthly payments by spreading them out over a longer timeframe. But underneath that simplicity lie critical trade-offs and unanswered questions. Here’s a narrative breakdown of what the proposal is, how it could affect buyers, and what experts are saying.
The proposal in a nutshell
The idea is that government-backed mortgage entities such as Fannie Mae and Freddie Mac would support home loans with a 50-year amortisation schedule
Supporters argue this would bring monthly payments down — making home buying accessible to more people, particularly younger would-be homeowners.
For example: in one scenario a $400,000 home at 6.25% interest might reduce the monthly payment from about $2,300 (30 years) to approximately $2,000 (50 years).
What’s driving the move
- Housing affordability is under strain: home-prices up, mortgage rates elevated, and many potential buyers finding it hard to qualify.
- The administration views extending term length as one “weapon in a wide arsenal” to improve access to homeownership.
- Other measures are also under discussion, including portable or assumable mortgages, but the term-extension idea has garnered most attention.
The benefits: what it might deliver
- Lower monthly payment pressure. Spreading the same principal plus interest over more years reduces each month’s burden. In a tight market that can help some buyers qualify or stretch less each month.
- Potentially more buyers enter the market. If monthly cost is the barrier, extending term helps mitigate that.
- Flexibility in an expensive market. In high-cost regions where even 30-year payments are steep, a 50-year option could feel like relief.
The risks & drawbacks: what you give up
- Much higher total interest paid. In the example above, total interest paid on the 50-year loan could be nearly double a 30-year loan.
- Much slower equity build-up. Because early payments go mostly to interest, it will take far longer under a 50-year term to reduce principal and build real home-equity.
- Extending debt into retirement. If someone takes out a loan in their 30s, a 50-year term could stretch into their 70s-80s — reducing flexibility and increasing risk.
- May inflate home-prices without increasing supply. By making monthly payments slightly more manageable, demand could rise — but if supply doesn’t keep up, prices may be driven higher, negating the benefit.
- Legal / regulatory hurdles. Under current U.S. rules (such as the Dodd‑Frank Act Qualified Mortgage rule), mortgages longer than 30 years are excluded from some protections. Changing this would require legislative/regulatory action.
So… is it a good idea?
It depends on your perspective:
- For a buyer who genuinely cannot afford a 30-year payment and is confident they’ll stay in the home for the full term, it could help in the short run.
- But for many, the long-term consequences may outweigh the near-term savings: slower wealth accumulation, more total interest, greater risk of carrying debt deeper into life.
- Several housing economists argue that rather than extending terms, the policy focus should be on building more homes, reducing costs of production, and addressing supply constraints — since term-extension doesn’t address the root supply-side problem
What happens next
At this stage the 50-year mortgage proposal is just a concept. No formal plan has been finalised, and key details (interest-rates, eligibility, regulatory changes) remain unspecified.
If it moves forward, we can expect:
- Regulatory changes to allow longer-term mortgages to be backed by Fannie/Freddie.
- Lender evaluations of risk (longer term means more uncertainty).
- Possibly higher interest rates for 50 yr loans to account for increased risk.
- Monitoring of market effects: will this benefit first-time buyers or primarily shift burdens?
Bottom line
The 50-year mortgage idea isn’t inherently bad — it offers a trade: lower monthly payment in exchange for longer debt, slower equity build-up and total higher cost. If you’re evaluating whether it’s right for you, ask:
- How long do I expect to live in this home?
- Can I afford a 30-year payment now, or is the only way in via a longer term?
- Am I comfortable paying significantly more interest over time?
- What happens if home values stagnate or decline?
- Does the market I’m buying in offer alternative solutions (larger down payment, smaller home, different area) instead of simply stretching the term?
From a policy perspective, term-extension might help some buyers now — but housing experts caution that without tackling supply, cost of construction, zoning, and rate pressures, it stops short of a full solution