China’s Inflation Misses Forecast as Factory-Gate Deflation Extends Into Fourth Year
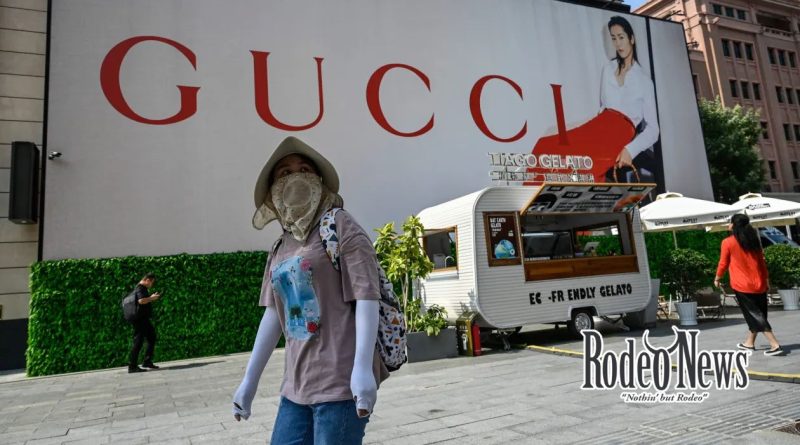
China’s consumer inflation slowed sharply in January, missing market expectations and reinforcing concerns that the world’s second-largest economy remains under persistent deflationary pressure despite official pledges of policy support.
Data released Wednesday by the National Bureau of Statistics showed that the consumer price index (CPI) rose just 0.2% from a year earlier. Economists had expected a 0.4% increase. The reading marked a significant cooling from December’s 0.8% rise — the strongest pace in nearly three years.
On a month-to-month basis, consumer prices edged up 0.2%, also below forecasts for a 0.3% increase.
The softer-than-expected inflation print highlights the fragile state of domestic demand, even as policymakers signal a more accommodative stance to stabilize growth and restore price momentum.
Core Inflation Also Loses Steam
Core inflation — which strips out volatile food and energy costs — climbed 0.8% from a year earlier, easing from December’s 1.2% increase. While the core measure remains positive, the moderation suggests underlying demand pressures are still subdued.
Analysts cautioned that seasonal factors may have distorted the January figures. This year’s Lunar New Year falls in mid-February, whereas last year’s holiday occurred in January, creating uneven comparisons.
Zhiwei Zhang, president and chief economist at Pinpoint Asset Management, said the shift complicates interpretation of the data.
“The mismatch in the timing of the Lunar New Year makes macro data comparisons more difficult,” Zhang noted.
Zavier Wong, market analyst at eToro, echoed that assessment, saying last January benefited from stronger holiday-related price effects that are absent this year.
“It makes more sense to assess January and February together rather than drawing conclusions from a single month,” Wong said.
Producer Prices Remain in Deflation
Meanwhile, factory-gate prices continued their prolonged decline, underscoring the deeper structural challenges facing China’s industrial sector.
The producer price index (PPI) fell 1.4% in January from a year earlier, slightly better than economists’ expectations of a 1.5% drop. The decline was less severe than December’s 1.9% contraction.
On a monthly basis, however, producer prices rose 0.4%, marking the fourth consecutive month of improvement. The uptick was partly attributed to rising global gold prices and modest stabilization in certain commodity markets.
Still, producer prices have now been in deflation for more than three years — a stretch that has eroded profit margins for manufacturers already grappling with weak consumer sentiment and trade-related disruptions.
Many firms have been caught in intense price competition as excess capacity across multiple industries floods the market with goods. Authorities have attempted to curb price wars, but overproduction remains a persistent issue.
Growth Achieved — But At a Cost
China’s economy expanded 5% last year, meeting Beijing’s official growth target. The performance was largely supported by resilient exports, particularly to non-U.S. markets, as companies diversified trade flows amid ongoing geopolitical tensions.
Yet beneath the headline growth figure, domestic demand has remained tepid. A prolonged property downturn continues to weigh on household wealth, while labor market uncertainty has dampened consumer confidence.
Since the end of the pandemic, China has struggled to generate sustained inflationary momentum, with property-sector weakness and cautious consumer spending keeping price pressures muted.
Rising Debt and Fiscal Constraints
Deflationary pressures have also strained government finances.
According to estimates from Morgan Stanley, China’s fiscal revenue-to-GDP ratio has fallen by 4.8 percentage points since 2021, dropping to 17.2%. At the same time, public debt has risen significantly.
The country’s public debt-to-GDP ratio is projected to reach 116% in 2025 — up roughly 40 percentage points since 2019. While still below the United States’ federal debt-to-GDP ratio of 124%, the rapid increase underscores mounting fiscal constraints.
Chetan Ahya, Morgan Stanley’s chief Asia economist, noted that policymakers continue to prioritize investment-led growth over direct consumption stimulus.
Authorities view consumption support as a “one-time boost” that could add to long-term debt burdens, he said, suggesting that broad-based fiscal handouts remain unlikely.
Policy Support in Focus
Top leaders are expected to announce key economic targets and policy priorities at next month’s annual parliamentary session, a closely watched event for investors.
In a policy report issued Tuesday, the People’s Bank of China reaffirmed its commitment to implementing “appropriately loose” monetary policy. The central bank said it aims to support economic stability and guide prices toward what it described as a “reasonable recovery.”
Whether that approach will be sufficient to reverse entrenched deflationary forces remains uncertain.
For now, January’s subdued inflation data signals that the path to sustained price growth — and stronger domestic demand — may prove slower and more uneven than officials had hoped.